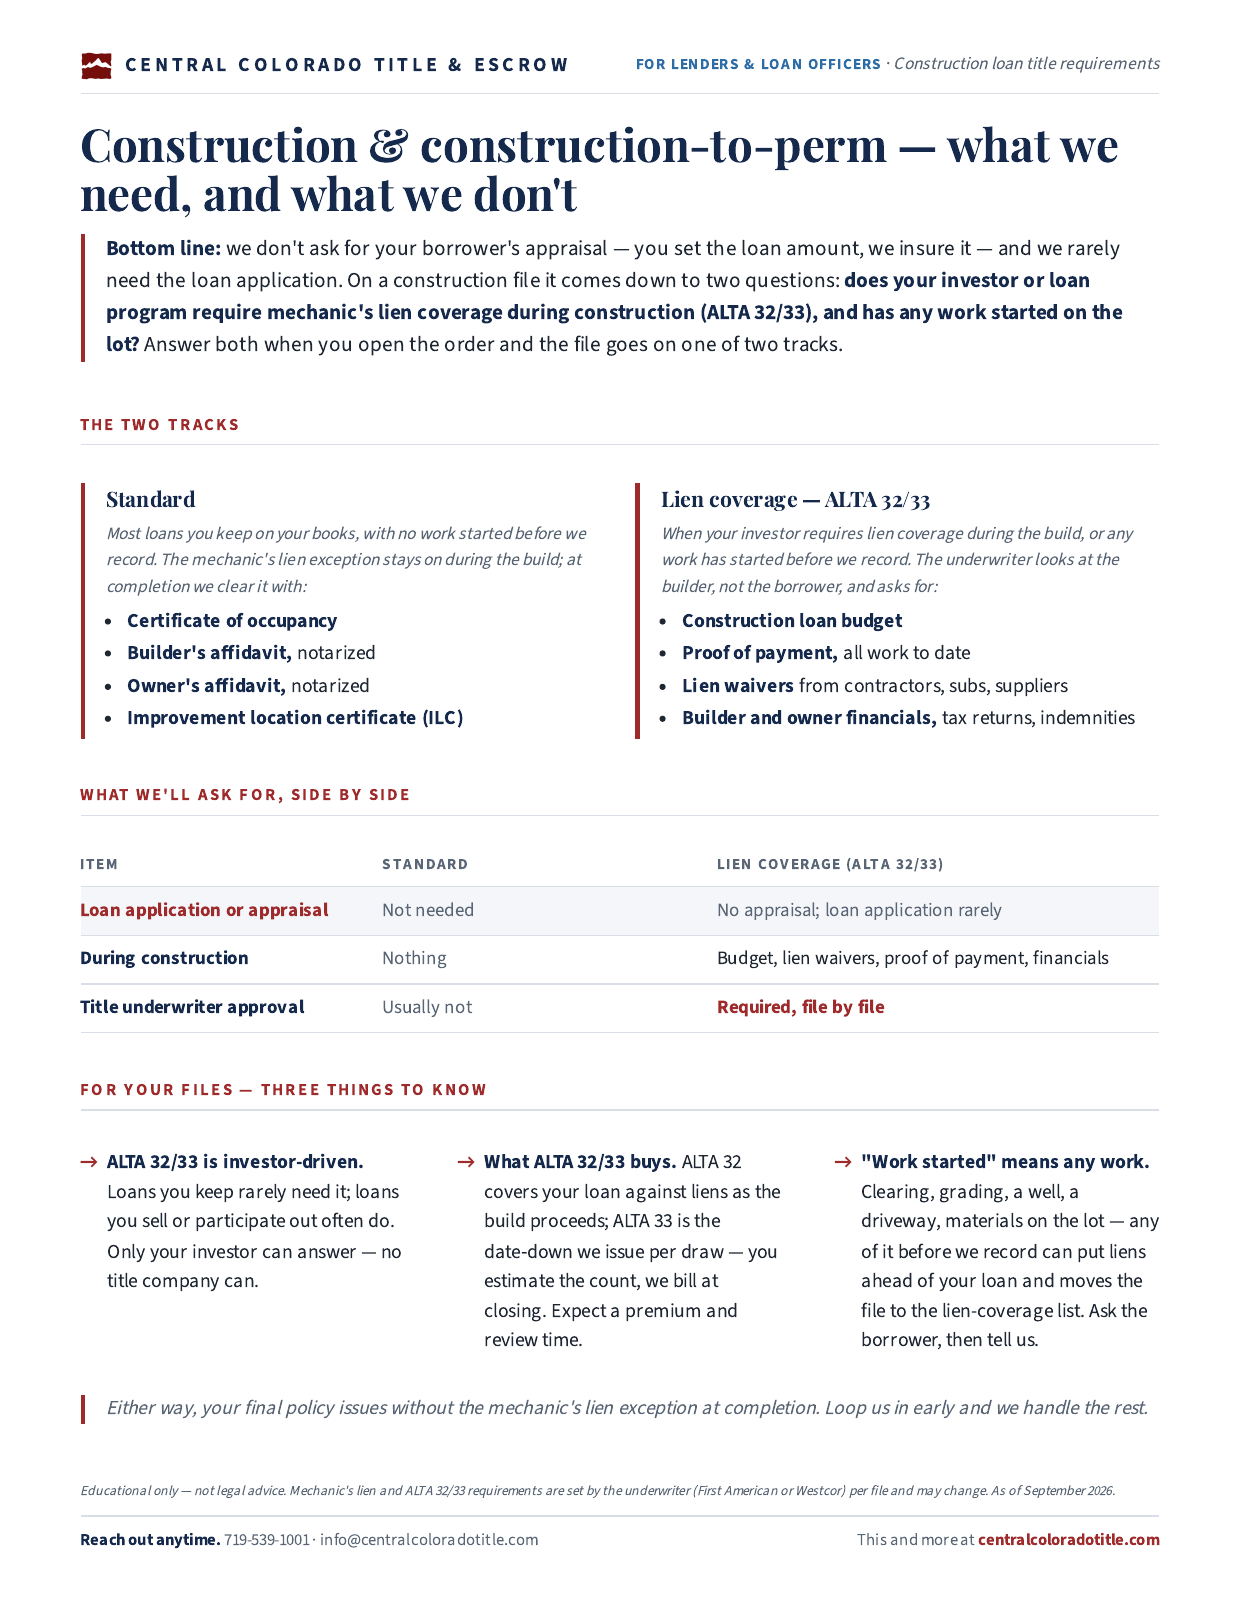
We don’t ask for your borrower’s appraisal, and we rarely need the loan application. Two questions decide the file: does your investor require ALTA 32/33, and has any work started on the lot?
Answer both questions when you open the order and the file goes on one of two tracks. Either way, your final policy issues without the mechanic’s lien exception once the build is complete.
| Item | Standard | Lien coverage (ALTA 32/33) |
|---|---|---|
| Loan application or appraisal | Not needed | No appraisal; loan application rarely |
| During construction | Nothing | Budget, lien waivers, proof of payment, financials |
| At completion | Certificate of occupancy, affidavits, ILC | Certificate of occupancy, affidavits, ILC |
| Title underwriter approval | Usually not | Required, file by file |
Not the appraisal — you set the loan amount, we insure it. The loan application only rarely, and only if the underwriter asks on a lien-coverage file.
ALTA 32 insures your construction loan against mechanic’s liens as the build proceeds. ALTA 33 is the date-down endorsement issued for each draw, extending coverage to the funds you’ve advanced.
Tell us with the order. In Colorado a lien’s priority runs from the first work on the project, so anything done before your deed of trust records can put liens ahead of your loan. The file moves to the lien-coverage list even if your investor didn’t ask for ALTA 32/33.
You send us the certificate of occupancy, the notarized builder’s and owner’s affidavits, and an ILC. We clear the mechanic’s lien exception and your final policy issues without it.
Educational only — not legal advice. Mechanic’s lien and ALTA 32/33 requirements are set by the underwriter (First American or Westcor) per file and may change. As of September 2026.